A projection is credible when a reviewer can move one assumption and follow its effect through revenue, profit, working capital, and cash. Decimal places do not improve a model whose customer counts, hiring dates, and collection days are disconnected.
Write assumptions once
Create dated input blocks for opening customers, new customers, churn, price, hiring dates, compensation, payment terms, capital spending, tax, and financing. Formulas should reference those blocks; a hard-coded growth rate hidden inside a revenue cell cannot be reviewed.
State units beside inputs: nominal USD, million rial, accounts, days, or full-time equivalents. Keep original transaction currency and a dated translation table; never mix rial payroll and dollar cloud spend in one unlabeled row.
Build the operating engine
Worked September 2026 case: opening customers 200, new customers 30, churned customers 12, so ending customers = 200 + 30 - 12 = 218. Using the simple average (200 + 218) / 2 = 209 and USD 200 recognized monthly revenue per active account gives USD 41,800.
Assumptions: additions and churn occur evenly through the month, every active account has the same USD 200 price, no discounts or usage charges exist, and IFRS 15 performance obligations are satisfied ratably. A daily cohort model should replace the average when timing is material.
Connect profit, balance sheet, and cash
Revenue flows to the income statement; unpaid revenue increases receivables on the balance sheet; collections reduce receivables and increase cash. Payroll and vendor accruals follow the same recognition-versus-payment bridge. Retained earnings must carry modeled profit, not a plug.
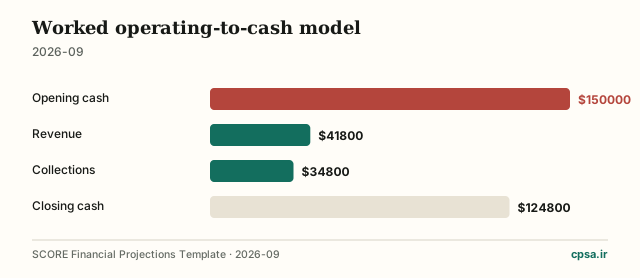
Worked cash steps: opening cash USD 150,000 + customer collections USD 34,800 - operating payments USD 60,000 = closing cash USD 124,800 at 30 September 2026. The USD 7,000 gap between revenue and collections increases receivables, assuming no write-off or prior-period collection.
- Opening cash150,000 $
- Revenue41,800 $
- Collections34,800 $
- Closing cash124,800 $
SCORE Financial Projections Template (2026-09). Worked nominal-USD month; values are model assumptions, not forecasts for a real company.
Use scenarios to expose decisions
Sensitivity one: if churn doubles from 12 to 24 while new customers stay 30, ending customers become 206, average customers 203, and revenue USD 40,600. Sensitivity two: if collections fall by USD 10,000, closing cash becomes USD 114,800 even though recognized revenue is unchanged.
Tie each downside to a decision date: freeze a hire before its offer, cut a campaign before commitment, renegotiate payment terms, or raise capital before minimum cash. FAST modeling guidance improves structure and readability, but governance comes from named owners and preserved scenario versions.
Frequently asked questions
How many years should the model cover?
Use monthly detail through the decision horizon, often 18–24 months, then quarterly detail only when useful.
Should best case be the base case?
No. Base should reflect the most supportable assumptions; upside and downside remain separate.
Why does profit differ from cash?
Recognition timing, receivables, payables, capital expenditure, financing, and noncash charges create the bridge.
How should the model handle currency?
Keep each flow in transaction currency, translate with dated disclosed rates, and test rate sensitivity separately.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in An Accurate Projection Is Traceable, Not Precise-Looking is attributed. Where a number is an estimate rather than a census, the note says so.
- SCORE financial projections templateIntegrated projection structure for small businesses.
- SBA financial management guideFinancial statements and cash-management fundamentals.
- IFRS Foundation — IFRS 15Revenue-recognition principles for customer contracts.
- FAST Standard OrganisationSpreadsheet-model structure and readability conventions.
Primary sources used for this edition.
The bottom line
Change churn once and follow it through customers, revenue, receivables, profit, and cash.
If you want the adjacent decisions after An Accurate Projection Is Traceable, Not Precise-Looking, start with Budget management, Financial metrics, Cost structure, Cash forecasting.


