The useful question is not whether an invoice is overhead. It is what makes the amount move. Hosting may vary with transactions, support may jump when tickets cross a staffing threshold, and rent may remain fixed until the lease ends.
Name the behavior of each cost
Use four buckets: fixed within the planning range, variable per unit, step-fixed after a capacity threshold, and discretionary. Payroll is not automatically fixed: contractor hours can vary while a support hire arrives as a step at a ticket threshold.
Attach a driver and owner to each material line. IAS 2 clarifies which conversion costs belong in inventory, while IAS 38 prevents teams from casually treating every development expense as an asset; accounting treatment and cash behavior must remain separate columns.
Calculate contribution before break-even
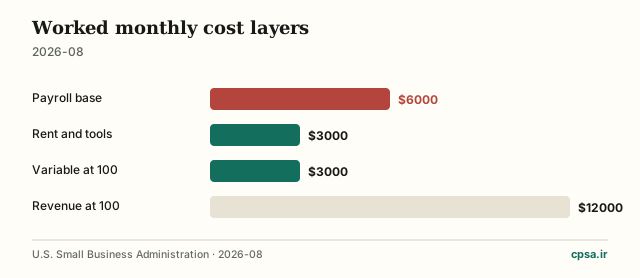
Worked case, as of August 2026: price is USD 120 per account per month; variable delivery cost is USD 30; monthly contribution is therefore USD 90. With USD 9,000 of fixed operating cost, break-even volume is 9,000 / 90 = 100 active paying accounts.
The calculation assumes no annual prepayment, no bad debt, stable unit delivery cost through 100 accounts, and all figures in nominal USD excluding tax. Reconcile the model to invoices and payroll monthly; do not translate a rial ledger at a convenient historical rate.
- Payroll base6,000 $
- Rent and tools3,000 $
- Variable at 1003,000 $
- Revenue at 10012,000 $
U.S. Small Business Administration (2026-08). Worked monthly USD case; amounts are assumptions, not sector benchmarks.
Test the driver, not one percentage
Sensitivity: if variable cost rises from USD 30 to USD 45, contribution falls to USD 75 and break-even becomes 120 accounts. If fixed cost then adds a USD 3,000 support step at 110 accounts, the post-step break-even becomes 12,000 / 75 = 160 accounts.
This discontinuity matters more than a blanket ten-percent cut. Draw thresholds for support seats, cloud commitments, warehouse space, and compliance reviews so a sales plan cannot cross capacity without funding the next step.
Make currency and time explicit
For an Iranian startup, keep the operational ledger in rial and tag imported software or cloud commitments in their invoice currency. Revalue foreign-currency commitments at a dated, documented rate and show the translation difference separately from usage growth.
Review the map at the shorter of one month or the next capacity threshold. SBA’s startup-cost worksheet is useful for identifying categories, but management must convert that inventory into drivers, ranges, and dated decisions.
Frequently asked questions
Is payroll fixed or variable?
It depends on the decision range: salaries are often fixed for a month, contractor hours vary, and a new team is step-fixed.
Should development be capitalized?
Only when the applicable IAS 38 recognition criteria are met; cash still leaves when paid.
Which exchange rate belongs in the model?
Use a dated, documented rate appropriate to the payable and disclose it; test a weaker-rial case separately.
Is break-even the same as cash survival?
No. Contribution break-even ignores collection timing, debt service, and capital purchases.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in A Cost Structure Is a Map of Drivers, Not an Expense List is attributed. Where a number is an estimate rather than a census, the note says so.
- SBA startup-cost guideCost-category inventory and startup-cost worksheet.
- IFRS Foundation — IAS 2Inventory and conversion-cost treatment.
- IFRS Foundation — IAS 38Recognition criteria for intangible assets.
- IRS Publication 535Business-expense definitions; jurisdiction-specific tax advice is excluded.
Primary sources used for this edition.
The bottom line
Put the driver beside every material cost and redraw the map before the next capacity step.
If you want the adjacent decisions after A Cost Structure Is a Map of Drivers, Not an Expense List, start with Startup budgeting, Financial modeling, Financial metrics, Cash forecasting.


