Insurance is neither a universal startup checklist nor a substitute for controls. One policy may be compulsory because of employment law, another promised in a customer contract, another required by a landlord or lender, and another purchased voluntarily for a loss the company cannot retain. The file should show which reason supports each policy.
Separate legal, contractual, and voluntary requirements
Build a requirements register by employing entity, worker location, vehicle, premises, licence, customer contract, lease, loan, and investor document. Workers' compensation in the United States is largely administered through state systems, while federal programs cover specified groups. In the UK, employers' liability rules state a minimum cover subject to their scope and exemptions. Neither statement answers another country's requirement.
Contract insurance clauses need their own review. Required limits, additional-insured status, primary wording, waiver of subrogation, insurer rating, territory, certificate timing, and notice obligations may exceed what the law requires. A certificate summarizes insurance; it does not silently amend the policy or prove every demanded endorsement exists.
Match policy architecture to the loss
List credible loss scenarios before requesting quotes: employee injury, property damage, product injury, professional error, privacy event, network interruption, theft, founder litigation, employment claim, cargo loss, or flood. For each, estimate who could claim, which entity caused the act, where it happened, the plausible accumulation, and which controls reduce frequency or severity.
Then compare insuring agreements, definitions, named insureds, additional insureds, exclusions, sublimits, deductibles or retentions, defence costs, aggregation, territory, governing law, and insurer security. General liability, property, professional liability, cyber, directors and officers, employment practices, crime, product, cargo, and business interruption policies solve different loss problems and often overlap imperfectly.
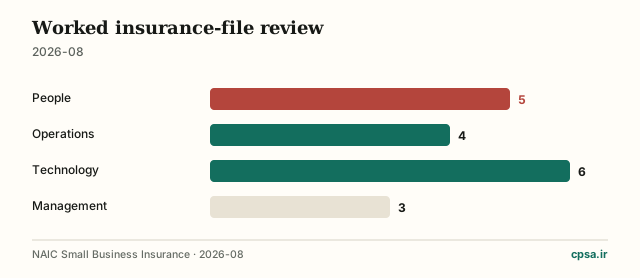
- People5 count
- Operations4 count
- Technology6 count
- Management3 count
NAIC Small Business Insurance (2026-08). Worked example: documents reviewed for four coverage lanes; counts are not recommended limits.
Read the trigger, period, and notice mechanics
Occurrence coverage generally focuses on when covered injury or damage occurred; claims-made coverage commonly depends on when the claim is first made and reported, subject to the exact wording, retroactive date, continuity, and extended reporting terms. Do not let a claims-made policy lapse or change insurers without analyzing prior acts, pending circumstances, and tail options.
Create a notice protocol that reaches legal, security, HR, finance, operations, broker, and insurer as relevant. A demand letter, subpoena, regulator inquiry, employee complaint, outage, lost device, or threat can trigger notice before liability is established. Preserve the policy version, chronology, notices, acknowledgements, reservation-of-rights letters, consent to defence costs, and proof of loss.
Worked renewal: test the file, not just the premium
Worked example: a SaaS company adds a UAE subsidiary, UK employees, a US hospital customer, and a new payment feature. Renewal review opens separate questions about insured entities, employers' liability and local workplace cover, professional and cyber wording, contractual limits, territorial reach, regulatory exclusions, payment activity, prior acts, and incident disclosure. No coverage conclusion follows without the policies and local facts.
Reviewed 21 August 2026, this module is not insurance, legal, tax, employment, or risk advice and does not recommend a limit, carrier, or policy form. Requirements and policy interpretation vary by jurisdiction, regulator, contract, insurer, wording, and facts. Use licensed brokers or advisers and qualified counsel in every relevant jurisdiction; only the issued policy and endorsements state coverage.
Frequently asked questions
Which insurance is legally required for every startup?
There is no universal answer. Entity, worker location, vehicles, premises, licences, and activities determine compulsory cover.
Does a certificate of insurance prove coverage?
It is evidence to review, not the full contract. Check the policy and required endorsements.
What is the key risk when changing a claims-made policy?
A gap in retroactive date, continuity, reporting, or prior-acts treatment can leave an earlier act uncovered.
Does cyber insurance replace security controls?
No. Controls affect loss, underwriting, policy conditions, exclusions, response, and evidence.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in Buy Insurance Against a Written Loss Map is attributed. Where a number is an estimate rather than a census, the note says so.
- NAIC Small Business InsuranceInsurance-regulator consumer guidance on common commercial coverage types.
- U.S. Department of Labor Workers' CompensationOfficial overview of state and specified federal compensation systems.
- UK Employers' Liability InsuranceOfficial UK requirement, minimum, scope, and exemptions.
- FEMA National Flood Insurance ProgramOfficial flood-insurance and hazard context for US property risk.
- SEC Cybersecurity Disclosure RulesOfficial disclosure context for covered public companies; not an insurance mandate.
Primary sources used for this edition.
The bottom line
At renewal, ask what changed in the company before asking what changed in the premium.
If you want the adjacent decisions after Buy Insurance Against a Written Loss Map, start with Contract requirements, Industry regulation, Compliance audit, Cross-border legal.


