For a startup, deal flow is the controlled movement of suitable investors from researched fit to an explicit financing decision. A CRM full of names is not a pipeline. Each live record needs a reason for fit, permission basis, evidence sent, named owner, dated next decision and probability derived from observable state.
Define stages by investor behavior
Use entry and exit evidence: researched fit requires mandate, stage, geography and check-size evidence; conversation requires consent and a scheduled exchange; diligence requires a requested artifact list; partner review requires a named decision forum; term sheet requires executable economics, control and closing conditions. Avoid stages such as warm, interested or promising.
NVCA reports 15,352 US venture deals in 2025, including 5,049 pre-seed or seed deals. Those counts describe completed or reported market activity, not the probability that one founder moves from email to funding. Never import market volume as a CRM conversion rate.
- Researched fit48 count
- Consented conversation24 count
- Diligence opened11 count
- Partner decision6 count
- Executable term sheet2 count
SEC exempt offerings (labeled example). Illustrative founder pipeline; no stage is a market benchmark.
Make one record the source of truth
Store organization, fund, person, role, mandate evidence and date, introducer, consent basis, conflicts, last evidence shared, unanswered question, owner, next decision, target date, state reason and source links. Keep subjective notes separate from factual fields so a mood cannot silently change the forecast.
Minimize personal data. Record only what is necessary for the financing process, define retention and deletion, restrict access, and correct inaccurate records. GDPR and UK ICO guidance apply only where their territorial rules are met, but purpose limitation and data minimization remain sound operating disciplines elsewhere.
Diagnose the bottleneck weekly
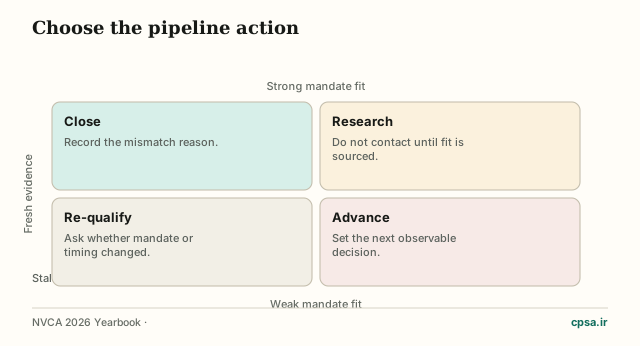
Review transitions by source, mandate segment and cohort date. A low researched-fit-to-conversation transition points to targeting or message failure. A healthy conversation rate with weak diligence entry points to evidence or timing. Many term sheets with few closes point to terms, compliance, financing proof or closing conditions.
In the labeled funnel, 48 researched accounts produce six partner decisions and two executable term sheets. Those numbers are diagnostic inputs, not a recommended funnel. The decision is to repair the largest evidence-backed leak before adding more names at the top.
Forecast cash, law and capacity separately
Forecast three dates: investment decision, definitive-document signature and cash availability. Weighting a friendly meeting as cash hides diligence, committee, legal and transfer risk. Keep a downside runway plan that assumes every undated record contributes zero.
US exempt-offering rules do not govern Iran, UAE, UK, EU or other offerings. Solicitation, broker activity, privacy, sanctions, foreign ownership, exchange controls and filings vary by issuer, investor, communication and place. Counsel must approve the process; a CRM stage never proves legal compliance.
Frequently asked questions
What is the first pipeline stage?
Researched mandate fit with a dated source—not a scraped name.
Should I assign probabilities?
Only to observable states with your own historical calibration; otherwise forecast dates and scenarios.
When should a record be closed?
At an explicit no, mandate mismatch, missed decision date without a new one, or withdrawn consent.
Can the CRM hold personal notes?
Only necessary, accurate, access-controlled data under the applicable privacy basis.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in Manage Fundraising Deal Flow as a Decision Ledger is attributed. Where a number is an estimate rather than a census, the note says so.
- NVCA 2026 YearbookUS deal population and stage counts.
- SEC exempt offeringsOfficial US offering pathways and communication context.
- EU General Data Protection RegulationOfficial EU data-processing law.
- UK ICO data-protection principlesOperational guidance on purpose and data minimisation.
Primary sources used for this edition.
The bottom line
A pipeline is healthy when every live record has a reason, an owner and a dated decision.
If you want the adjacent decisions after Manage Fundraising Deal Flow as a Decision Ledger, start with Angel relationships, IC presentations, Investment syndicates, Funding rounds.