An investment committee presentation is the final compression of weeks of underwriting. The presenter’s job is not to repeat the data room; it is to show what must be believed, which evidence supports it, what could break it, and what decision or condition follows.
Reconcile the room before the deck
Obtain the sponsor’s current investment memo, decision ask, open diligence list, ownership model, and proposed conditions. Reconcile names, dates, cohort definitions, revenue recognition, cash, cap table and market denominator. A founder should not discover in committee that the sponsor underwrote a different ARR or geography.
Write five or fewer decision claims in the illustrative case: urgent buyer pain, retained use, repeatable acquisition, defensible delivery, and a financing path. Attach an owner, primary evidence, contrary evidence and confidence score. Five is a presentation choice here, not a reported industry rule.
- Customer pain5 score
- Retention4 score
- Sales repeatability3 score
- Security readiness2 score
- Exit path1 score
ILPA reporting guidance (labeled example). Illustrative evidence confidence by claim; scores are internal decisions, not benchmarks.
Answer the downside in the main narrative
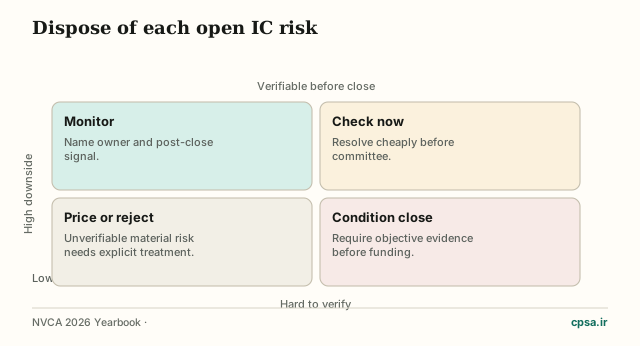
Do not exile churn, concentration, regulatory exposure, founder dependence, security gaps or bridge risk to backup slides. State the exposure, observed evidence, maximum plausible damage, mitigation owner, trigger date and residual risk. Committees price candor; surprise destroys the sponsor’s credibility as well as the founder’s.
In the labeled case, two unresolved red risks do not automatically mean reject. They mean the committee must choose among rejection, a priced risk, a closing condition, a post-close covenant, or more diligence. The correct treatment depends on reversibility and whether the evidence can exist before close.
Rehearse retrieval, not recitation
Run one closed-book rehearsal where a partner interrupts after every claim: What is the denominator? Which contract proves it? What changed since the memo? What would make you walk away? Record every answer that requires a later lookup and repair the source index, not just the speaking notes.
A 35-minute rehearsal is merely the worked input. The meaningful constraint is full retrieval under interruption while preserving answer ownership between founder, sponsor, technical reviewer and counsel. Duplicate answers create contradiction; silent ownership creates dead air.
Respect mandate, law and evidence population
A private fund’s mandate, side letters, concentration limits, reserve policy and conflicts shape what its committee can approve. SEC material is US regulatory context; ILPA templates reflect institutional private-capital reporting, and NIST is a voluntary cybersecurity framework. None supplies a universal IC scorecard.
The NVCA count covers US venture deals reported for 2025; it does not reveal committee submissions, rejection rates or Iranian outcomes. Fund governance and offering law differ across the US, Iran, UAE, UK, EU and other jurisdictions. Counsel and the fund’s governing documents control the actual decision process.
Frequently asked questions
Should founders see the IC memo?
At minimum reconcile the factual record, thesis and open risks with the sponsor; fund policy may restrict the full memo.
How many backup slides are enough?
No universal count. Index primary evidence to known decision questions and open diligence.
What if a metric changed yesterday?
Disclose the timestamp, old value, new value and cause before questions begin.
Who answers legal questions?
Assign counsel or the deal lead; founders should state facts and avoid improvising legal conclusions.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in Prepare the Investment Committee Decision, Not a Longer Pitch is attributed. Where a number is an estimate rather than a census, the note says so.
- NVCA 2026 YearbookUS venture deal population for 2025.
- SEC private fundsOfficial US private-fund context.
- ILPA templates and standardsInstitutional reporting and diligence references.
- NIST Cybersecurity Framework 2.0Risk-governance vocabulary for technical diligence.
Primary sources used for this edition.
The bottom line
If the committee cannot see what would disprove the thesis, it is hearing advocacy rather than underwriting.
If you want the adjacent decisions after Prepare the Investment Committee Decision, Not a Longer Pitch, start with IC decision-making, Investor diligence, Deal flow management, Term-sheet tactics.