An angel relationship is not a long sales sequence. It is accumulated evidence that the founder reports honestly, uses access carefully, and can make progress between conversations. Build that record before a financing window forces every interaction into an ask.
Map fit before asking for access
Build a short thesis card for each angel: sectors understood, stage, geography, check source, conflicts, follow-on appetite, and the people who can verify the fit. An operator with healthcare procurement experience may be valuable before investing; a famous consumer angel may be the wrong reader for a regulated B2B sale.
The SEC thresholds describe who may qualify for many US private offerings; they do not prove sophistication, interest, or eligibility elsewhere. A $1 million net-worth threshold excluding the primary residence and a $200,000 individual-income test are US legal facts, not a global definition of a good angel.
Use updates as an evidence ledger
Send an update only with permission. Keep the same fields: cash date, one operating metric with cohort or denominator, what changed, one miss, one next experiment, and one bounded request. Consistency lets the reader compare periods; admitting a miss before being asked builds more trust than polishing every line green.
A 30-day cadence is a labeled operating example, not a universal benchmark. Enterprise procurement may need quarterly evidence; a live financing may need weekly process notes. Choose the interval that produces new evidence, state it once, and stop sending when the recipient withdraws permission.
- Receive update1 score
- Give customer feedback2 score
- Make one introduction3 score
- Review a round5 score
Angel Capital Association (labeled example). Illustrative evidence required before escalating an ask; not a market benchmark.
Run the first meeting as a diagnosis
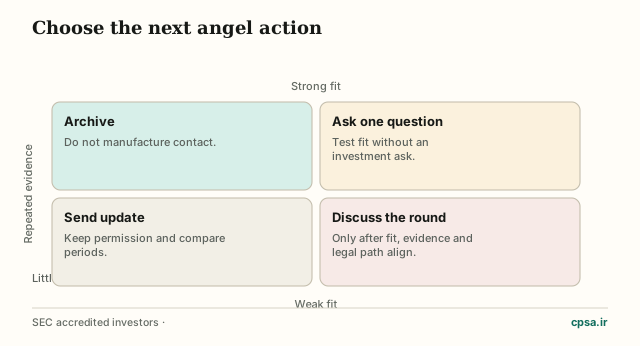
Open with the decision the company must make, not a biography. Ask which assumption the angel would falsify first, which comparable is misleading, and what evidence would earn another conversation. Record advice, owner, due date, and whether you accepted it; untracked advice becomes social debt without learning.
Illustrative decision: three verified signals—relevant operating history, a useful critique, and consent to updates—justify asking for one customer introduction. They do not justify asking for capital or a cascade of introductions. The permission ladder prevents a weak contact from being treated as a committed investor.
Separate relationship-building from an offering
Once a conversation becomes an offer to sell securities, fundraising communications, investor eligibility, disclosure, intermediaries, and filing obligations depend on governing law and exemption. In the United States, Rule 506(b) and Rule 506(c) treat solicitation differently. Friendly language does not remove securities-law obligations.
SEC material applies to US offerings and ACA practice reflects organized angel communities, not every private investor. Iranian, UAE, UK, EU, Canadian and other regimes differ on solicitation, foreign ownership, exchange controls, sanctions, tax and enforceability. Qualified local counsel must approve an actual raise; relationship advice is not legal or investment advice.
Frequently asked questions
How early should I meet angels?
When you have a real decision or evidence to discuss, not a synthetic six-month countdown.
Should every update contain an ask?
No. Use a bounded ask only when the recipient is unusually suited to it.
Is a warm introduction required?
No, but the introducer can verify fit. A specific cold note can outperform a vague warm one.
Can an interested angel invest immediately?
Interest is not eligibility or a compliant offering. Confirm the governing exemption and documents with counsel.
Answers to the questions this topic usually leaves hanging.
How we sourced this
Every statistic in Build Angel Relationships Before You Need the Check is attributed. Where a number is an estimate rather than a census, the note says so.
- SEC accredited investorsOfficial US qualification categories and thresholds.
- SEC exempt offeringsOfficial US exemption and solicitation overview.
- Angel Capital AssociationAngel-investment process and education context.
- OECD Financing SMEs and Entrepreneurs 2024Cross-country limits and financing conditions.
Primary sources used for this edition.
The bottom line
A useful angel relationship is a record of earned permissions, not accumulated coffee meetings.
If you want the adjacent decisions after Build Angel Relationships Before You Need the Check, start with Types of investors, Investment syndicates, Founder diligence, Funding rounds.